The online betting platforms had been forecasting it for over a month, but last week confirmed it. Midterm elections were a clean sweep for Democrats, who flipped both the House and the Senate. They also took a majority of governorships for the first time in 16 years. Five governorships flipped from Republican to Democrat, several in long-time Republican strongholds.
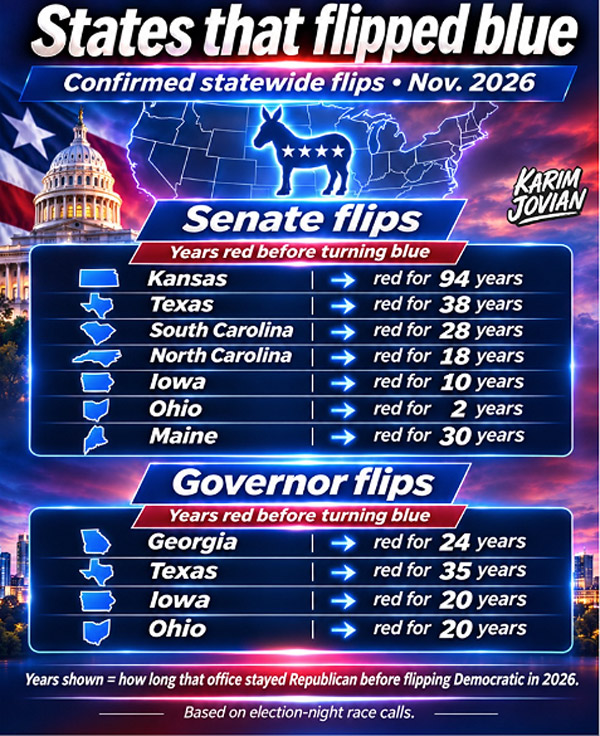
Source: @Karimjovian
With the certainty of the post-election results came a classic relief rally on Wednesday, with the Dow up about 3%, reportedly its best post-midterm day since 1982. Thursday was a different story as market participants tried to price in the full impact of the wave of Democratic wins. The Dow lost roughly 1,800 points (-3.4%), the S&P 500 fell about 4.4%, and the Nasdaq dropped 5.5%, its worst day in 19 months and into correction territory. The semiconductor index fell more than 12%, likely driven by the expectation that Democrats are expected to try to slow down the infrastructure buildout for AI. One thing we would point out is that this short-term volatility is largely based on sentiment and not fundamentals. We would need to see more data to believe that the current fundamentals of the market have changed materially.
A Hot Jobs Report Gives the Fed Room; the Bank of England Expects 5% Inflation
Friday’s October jobs report showed payrolls up 165,000 against a consensus of about 65,000. September was revised up to 60,000 from 29,000, and unemployment ticked down to 4.1%. Wage growth came in at 3.1%, a solid number but still below inflation, so real wages remain negative. The continued strength in the jobs market gives the Federal Reserve plenty of room to potentially hike again in the near term. CME’s FedWatch is showing just north of 80% probability of another hike in December. A lot can happen between now and December 9th, but as of now, markets are pricing in a rate hike.
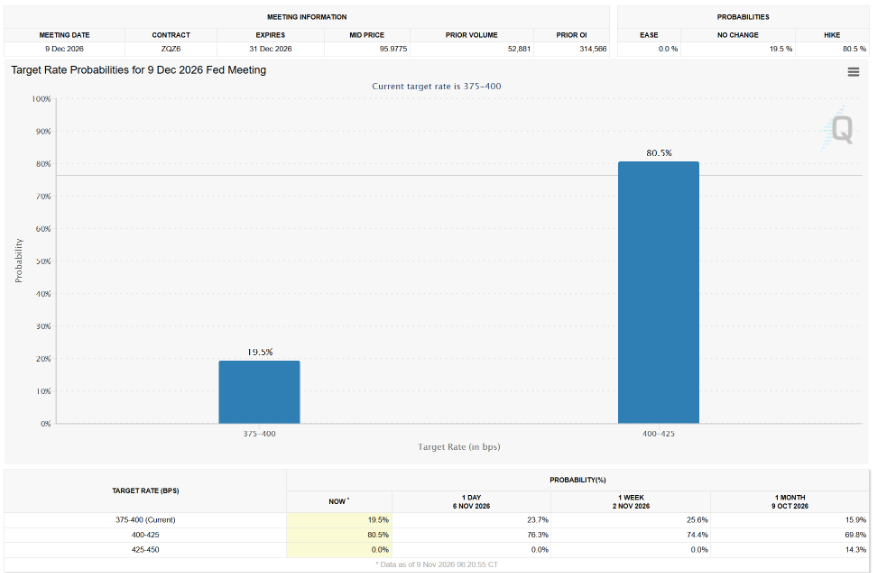
Source: CME FedWatch
Looking overseas, the Bank of England voted to increase interest rates by 25bp for the first time in more than three years to 4%. Historically speaking, the US and England’s rate paths have been similar, so this didn’t come as much of a surprise. One of the eight voting members wanted to increase it by 50bp as the central bank warned that inflation could reach 5% by mid-2027. While we don’t expect inflation in the US to accelerate to those levels, we continue to see sticky levels of inflation that is clearly a global problem.
Private Credit: Doomsday Hasn’t Shown His Face Yet
We haven’t discussed private credit for a while, but given all the headlines earlier this year, we felt like it would be timely to give a quick update. Direct lending performance has been under some pressure, which isn’t a surprise to us given the high historic flows over the last few years, lower spreads, loan repricing, redemption demand, and the deluge of negative headlines.
Diversified private credit funds on the other hand, are performing in line with what we anticipated earlier this year. Both have continued to accrue income while the broader bond market has gone sideways to lower as yields have moved higher. See below for performance of two diversified private credit funds (CELFX and NAIFX) compared to a direct lending fund (CCLFX) and the broader bond markets (AGG).
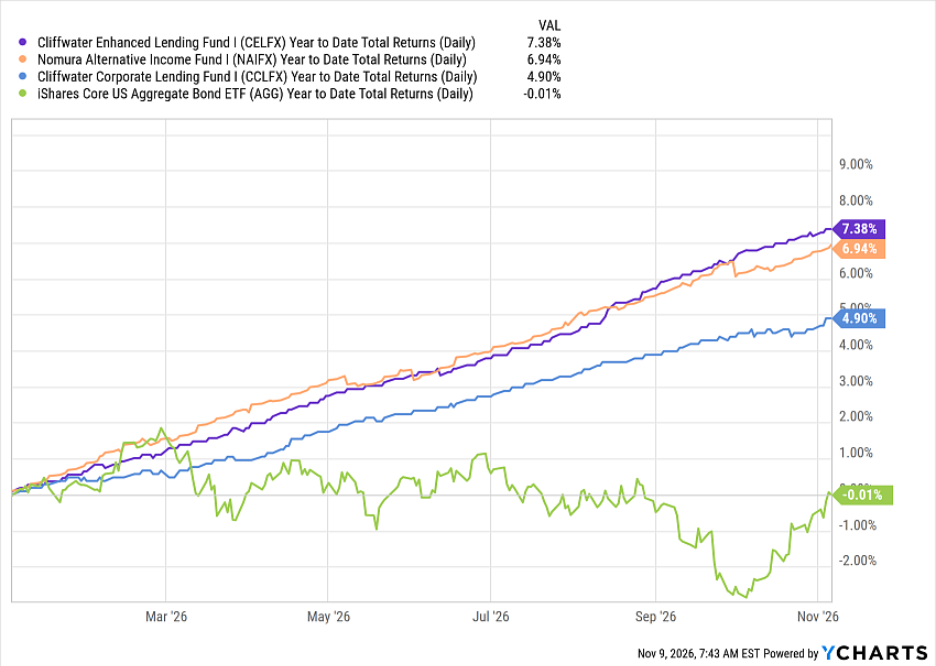
Source: YCharts
While interval funds, especially direct lending focused interval funds, continue to see some pressure due to redemption demands, the reality is that the semi-liquid nature of the structure is paying off for investors from a performance perspective. Had these funds been forced to sell loans during peak mania earlier this year, the performance story would be significantly different. We continue to view private credit as a great complement to traditional fixed income. While the reduced liquidity limits access to capital for investors, we continue to view the limits on liquidity as a feature to these strategies because it reduces forced selling in stressed markets.
Hope you have a great week, and remember, volatility is the price of admission.
Best,
Park City Investment Solutions Team
This material is for informational purposes only and does not constitute investment advice or a recommendation to buy or sell any security. Opinions expressed are as of the date of publication and are subject to change. Past performance is not indicative of future results.
